

Checkbook - Account Tracker

- 4.29K Reviews
- 3.6
- Downloads
- 100,000+
Our take on Checkbook - Account Tracker from Appgk
I like finance apps that stay focused, and Checkbook - Account Tracker takes that approach seriously. It is a straightforward Android app from TinyWork Apps designed to replace a paper checkbook register with a digital record of money moving in and out of an account. After using it, my impression is that its value comes from simplicity rather than from trying to become a complete banking or budgeting platform.
That distinction matters. If you want a clean place to record deposits, withdrawals, checks, and everyday spending, this app has a sensible purpose. If you expect automatic bank connections, investment tools, elaborate charts, or a full household budgeting system, you should look elsewhere. I found it most useful when I treated it as a careful transaction log rather than as an all-in-one financial manager.
What Checkbook - Account Tracker actually does well
The app belongs to the finance category, but its job is narrower than many modern money-management tools. It gives you a digital register where you can keep track of account activity manually. That makes it particularly familiar for anyone who has used a paper checkbook and wants the same basic habit on a phone.
The developer, TinyWork Apps, has kept the concept easy to understand. You do not need to learn a complicated budgeting system before entering a transaction. The central workflow is simple: record what happened, keep an eye on the running balance, and use the register to understand what should still be available in the account.
Best Parts of Checkbook - Account Tracker
Things to Keep in Mind About Checkbook - Account Tracker
That manual approach is both the app’s strongest quality and its biggest limitation. It gives me control over what gets recorded, but it also means the accuracy of the account depends on my consistency. A missed card purchase or forgotten cash withdrawal does not magically appear later. This is not a criticism unique to this app; it is the unavoidable trade-off of a manually maintained register.
The current version is 2.1.2, and the app supports Android devices running version 7.0 or later. Its Everyone content rating makes it broadly suitable from an age-classification perspective. It has passed the point of being an obscure experiment too: the app has more than 100 thousand installs, alongside an average rating of 3.6 from roughly 9 thousand ratings and about 4 thousand reviews. Those figures suggest a real user base, while also showing that the experience is not universally loved.
News and Features Related to Checkbook - Account Tracker

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
A practical register for people who still reconcile accounts
The best use case is someone who wants to know whether their apparent bank balance reflects money that has actually cleared, money already committed, or transactions that have not yet appeared in online banking. A paper register has traditionally handled that distinction well, and a phone-based version can be more convenient because it is available at the moment a payment happens.
For example, imagine I pay a utility bill by check or make a purchase with a card that will not post immediately. I can enter it while the event is fresh instead of trusting memory at the end of the week. Later, when I compare the register with the bank account, I have a record of what I expected to happen. That makes reconciliation less stressful than trying to reconstruct several days of spending from receipts and notifications.
Don't want to read the full review?
There is a useful mental shift here: I would not use the displayed balance as a replacement for checking the bank. I would use it as my available-after-commitments balance. That is a more honest and practical role for a manual checkbook app. The number can help me avoid spending money that is technically visible in the account but already reserved for a payment.
Where the free access fits into the decision
Checkbook - Account Tracker is free to install, which makes it easy to test the workflow without paying before knowing whether manual entry suits you. The app also includes in-app purchases ranging from $0.99 to $19.99 per item. Because the purchase options are not the same thing as the free installation, I would judge the app in two stages: first, whether the basic register fits my habits; second, whether any paid addition solves a problem I actually have.
Screenshots
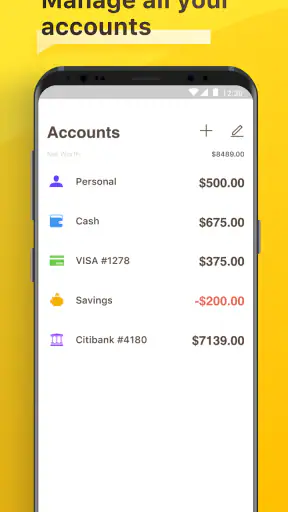
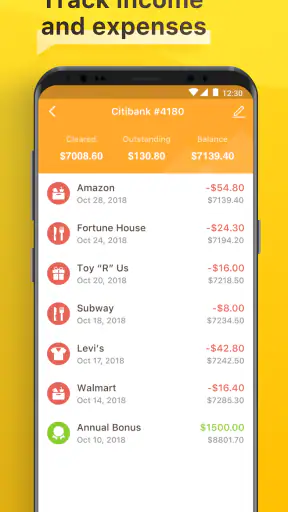
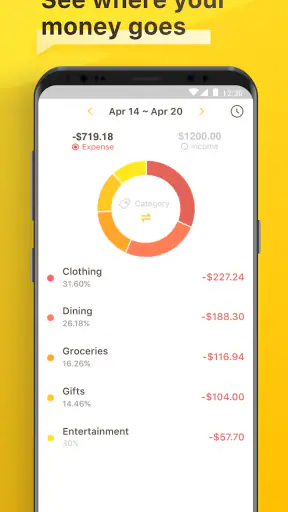
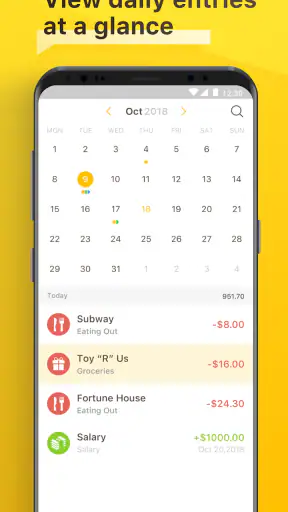
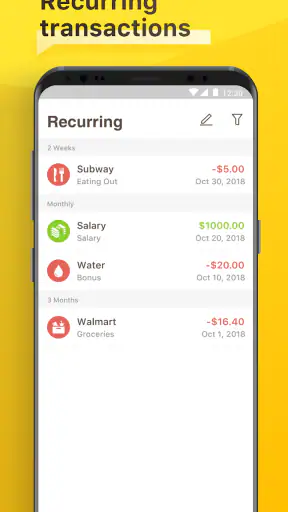
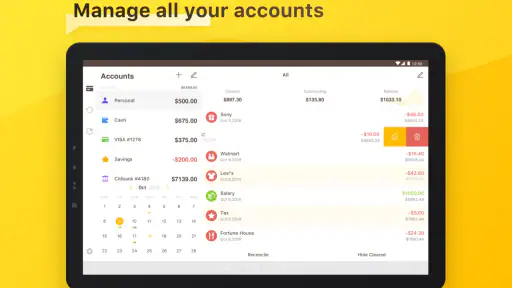
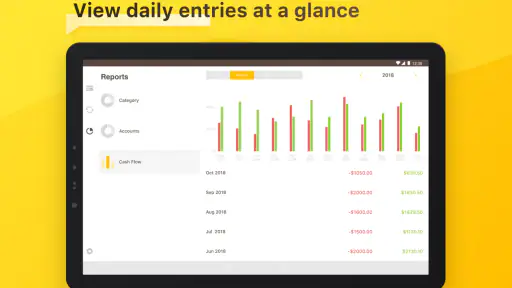
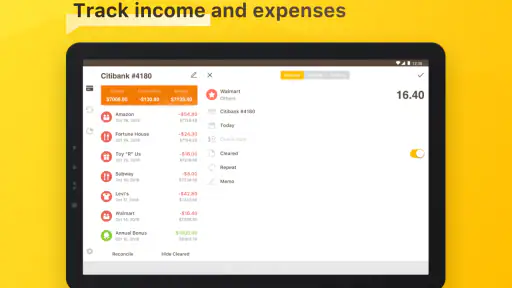
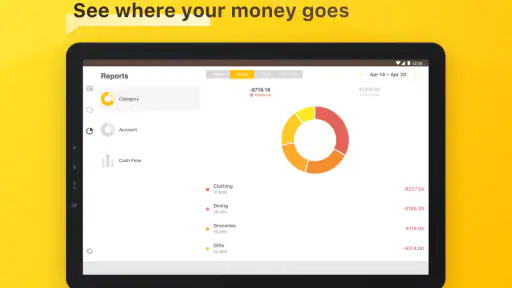
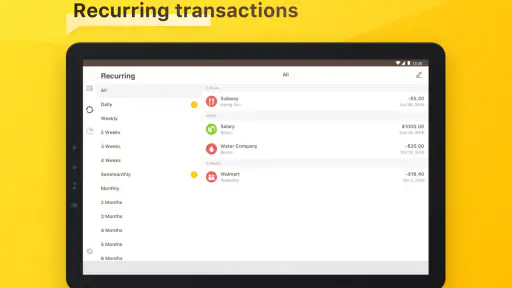
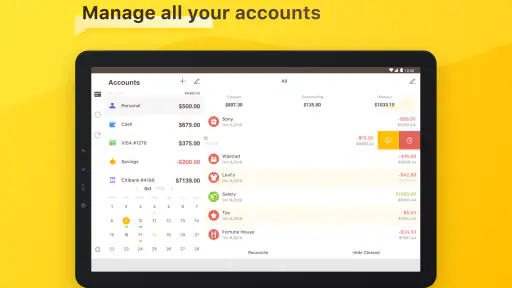
That is important for value. A free finance app can still cost time if its workflow makes every transaction annoying to enter. Conversely, a modest paid upgrade can be worthwhile if it removes a daily irritation. I would not buy anything immediately. I would use the free experience through a normal week, including several deposits, recurring bills, card purchases, and a reconciliation with the bank. Only then would I know whether the app earns a place in my routine.
The listed purchase range tells me that optional spending exists, but it does not by itself prove that every user needs it. I would avoid treating the highest available purchase as a required cost. The sensible approach is to start free, identify the exact limitation that affects you, and pay only if the relevant option clearly improves your record-keeping.
The small workflow choices that make a difference
My first tip is to enter transactions immediately, not when you think you will remember them later. A register is most reliable when it becomes part of the payment ritual. After writing a check, making a transfer, or paying with a card, recording it right away reduces the chance of a balance that looks healthy only because recent spending is missing.
My second tip is to use a regular reconciliation routine. I would compare the app with the bank account at a fixed point, such as after the weekly grocery trip or when the monthly statement arrives. The goal is not merely to see whether the totals match. It is to identify pending items, duplicated entries, and transactions I forgot to record. This turns the app from a passive list into an active checking tool.
A third useful habit is separating “money I have” from “money I can safely spend.” When a payment is entered before it clears, the register can remind me that the funds are already spoken for. That is especially helpful for people who use one account for rent, bills, and daily purchases. The app does not need to predict my future if I use it to document commitments myself.
I would also avoid using the register as a place to store sensitive financial details unnecessarily. A transaction description should be clear enough for recognition without becoming a detailed record that I would regret leaving on a phone. Simple labels such as a merchant or bill name are usually more practical than writing private account information into a note.
What it is like beside modern banking and budgeting alternatives
Compared with a bank’s own mobile app, this tool is better suited to personal tracking than to viewing official account activity. The bank remains the source I would trust for cleared transactions, available funds, alerts, and account security. Checkbook - Account Tracker is useful because it can represent my intentions and pending obligations before the bank’s record catches up.
Compared with a spreadsheet, the app is more convenient for quick entries on a phone. A spreadsheet can be more flexible for custom categories, formulas, yearly analysis, or shared household reporting, but it also demands more setup and maintenance. If I enjoy building my own financial system, a spreadsheet may offer greater control. If I simply want a register that is ready to use, this app is the less demanding option.
Compared with automated budgeting services, the difference is even clearer. Automatic services can reduce manual work by importing transactions and organizing spending, while a register gives me a deliberate record that I control. Automation is preferable for someone managing many accounts or wanting broad spending analysis. Manual tracking is preferable for someone who values a small, focused tool and is willing to enter information personally.
That makes the app a particularly reasonable choice for a single account, a checking account used for household bills, or a person who dislikes the complexity of larger finance platforms. It is less convincing for a family that needs synchronized access, detailed category reports, or a shared financial dashboard. In that situation, the convenience of a more comprehensive service may justify choosing something else.
Trade-offs I noticed before recommending it
The biggest friction is the need for discipline. The app cannot protect me from my own incomplete records. If I enter transactions days late, forget cash purchases, or fail to check pending payments, the balance becomes misleading. Someone who wants financial information to update automatically will likely find this approach too hands-on.
The average rating of 3.6 indicates a mixed reception rather than a universally smooth experience. I would read that as a reason to test the app with my actual routine instead of assuming that the paper-register idea will work for everyone. The concept is easy, but ease of concept does not guarantee that every device, habit, or expectation will feel equally comfortable.
There is also a risk of expecting more than the app’s core purpose. A register can show the history I enter, but that is not the same as a complete financial plan. It does not replace reviewing statements, watching for unauthorized activity, setting realistic spending limits, or keeping important records elsewhere when necessary. I see it as one layer of financial organization, not the entire system.
The purchase model deserves a little caution as well. Free access is a good starting point, but optional purchases mean I would inspect the available upgrade before assuming that every useful capability is included at no cost. I would make the decision based on a specific benefit, not on the vague idea that paying must make the app better. For a person who only needs a basic register, the free experience may already be enough.
Another trade-off is that manual entry can actually be a benefit for privacy-minded users, because it avoids making the app the center of an automated account connection workflow. At the same time, manual control means convenience is lower. I would choose this balance knowingly: less automatic collection and more personal effort.
Who gets the most value from this app
I would recommend it first to people who grew up with a paper checkbook register and want the same discipline without carrying a notebook. It also suits anyone who regularly has pending checks, delayed card transactions, or bills that need to be reserved before they officially clear. The app’s narrow focus can be reassuring when larger finance apps feel crowded with features I will never use.
It can also help someone who is trying to stop relying on a bank balance alone. A bank balance answers one question: what the institution currently shows. A personal register can answer another: what have I already committed to? Keeping both views in mind can make everyday decisions more deliberate, especially near payday or before several bills are due.
I would be more hesitant to recommend it to a person who rarely remembers to record purchases. I would also steer away from it for users who want automatic categorization, investment monitoring, debt payoff planning, or a detailed overview across several financial institutions. Those needs call for a broader finance product, even if that product takes longer to learn.
It is not the ideal choice for someone who wants a shared family workspace unless the app’s particular sharing behavior meets that need. I would not assume that a personal register automatically provides the collaboration tools required by couples or households. For shared finances, I would test that workflow carefully before making it the main record.
My verdict on whether it is worth trying
After weighing the free entry point, focused purpose, and manual effort, I see Checkbook - Account Tracker as a useful niche finance app rather than a universal recommendation. Its best quality is that it makes the old checkbook habit portable and easier to maintain in the moment. Its main weakness is inseparable from that design: the app is only as current as the person entering the transactions.
I would try it if I wanted a simple account register, especially for tracking pending payments and preventing a false sense of available money. I would keep the free version long enough to test real habits before considering any in-app purchase. If the register becomes part of my daily routine and a paid option addresses a clear annoyance, spending a small amount may make sense; otherwise, there is no reason to pay simply because the option exists.
My final recommendation is therefore conditional but positive. Choose it for deliberate, manual checking-account tracking; skip it if automation or full budgeting is your priority. TinyWork Apps has built something understandable for a specific job, and that focus is valuable when the job matches your needs. Just remember that it is a personal record, not an official bank ledger, and not a substitute for reviewing your real account activity.
For the right user, that modest role is enough. I would rather have a simple register I actually update than a sophisticated financial dashboard I avoid opening. If you are willing to record transactions as they happen and reconcile them regularly, this free Android finance app is worth testing. If you want your finances to organize themselves, a different category of tool will serve you better.
Checkbook - Account Tracker FAQ
What is Checkbook - Account Tracker used for?
Checkbook - Account Tracker is designed to help you monitor personal finances by recording income, expenses, transfers, and account balances in one place. During testing, it proved useful for keeping a running checkbook register and reviewing spending history without relying on a bank connection. It is especially suitable for users who prefer manually controlled budgeting and straightforward transaction tracking.
Does Checkbook - Account Tracker connect directly to my bank account?
The app is primarily focused on entering and organizing transactions rather than replacing your bank’s official application. Depending on the version and platform, available synchronization or import options may vary, so users should check the current store description before downloading. If automatic bank connectivity is important to you, confirm that supported institutions, formats, and security features meet your expectations first.
Can I manage multiple accounts and transaction types?
Yes, the app is intended for tracking more than one financial account, such as checking, savings, cash, or credit-related balances. You can generally record deposits, withdrawals, payments, transfers, and other common transaction types. This makes it practical for separating household finances, although the exact number of accounts, categories, and customization options may depend on the installed version.
Is Checkbook - Account Tracker suitable for budgeting and reviewing spending?
The application can support basic budgeting habits by allowing you to categorize transactions, inspect your spending history, and compare your recorded balance with your actual finances. It is most helpful when entries are made consistently and accurately. Users seeking advanced investment analysis, detailed financial forecasting, or sophisticated envelope budgeting may need a more specialized personal finance application.
Is my financial information safe when using the app?
Because a checkbook tracker may contain sensitive details about your finances, you should review its privacy policy, permissions, backup behavior, and available security settings before entering personal information. Avoid storing unnecessary account credentials or full banking details unless the app clearly explains how they are protected. Also remember that manually entered data should be backed up carefully to prevent accidental loss.













